

Accounting and finance teams have always played an important role in business. They manage payments, invoices, budgets, reports, taxes, payroll records, financial statements, audits, and cash flow. For many years, most of this work was done manually. Finance professionals used spreadsheets, paper documents, emails, calculators, and separate software systems to complete daily tasks.
Today, that is changing quickly.
Automation is transforming the way accounting and finance teams work. Tasks that once took hours or days can now be completed faster with digital tools, ERP systems, cloud platforms, artificial intelligence, and automated workflows. Instead of spending most of their time entering data, checking invoices, matching payments, and preparing repetitive reports, finance professionals are now expected to focus more on analysis, planning, compliance, and business decision-making.
This change does not mean accounting and finance jobs are disappearing. It means the role of finance professionals is changing. Companies still need people who understand numbers, rules, business processes, risk, and financial decisions. But they also need people who can work with modern finance systems and understand how automation supports accuracy, speed, and better reporting.
In simple words, automation is helping finance teams move from manual record-keeping to smarter financial management.
What Is Automation in Accounting and Finance?
Automation in accounting and finance means using technology to complete repetitive financial tasks with less manual effort. These tasks may include invoice processing, data entry, bank reconciliation, report generation, approval workflows, expense tracking, tax calculations, and financial closing activities.
For example, in a manual process, an employee may receive an invoice by email, download it, enter the supplier name, invoice number, amount, tax details, and due date into a system, send it to a manager for approval, and then forward it to finance for payment. This process can take time and may include mistakes.
With automation, the system can read invoice details, match the invoice with a purchase order, send it for approval, update payment records, and notify the finance team if something does not match.
Automation does not remove human control. Instead, it reduces repetitive work and allows people to focus on reviewing exceptions, solving problems, and making decisions.
Common examples of finance automation include:
- Accounts payable automation
- Accounts receivable automation
- Bank reconciliation automation
- Expense management automation
- Payroll data automation
- Financial reporting automation
- Budgeting and forecasting automation
- Tax calculation support
- Audit trail creation
- Financial close automation
- Workflow approvals
- Data validation and error detection
The main goal is to make finance work faster, more accurate, and easier to manage.
Why Accounting and Finance Teams Are Moving Toward Automation
Finance teams are under pressure from many directions. They must close books faster, produce accurate reports, support business decisions, manage compliance, reduce errors, and control costs. At the same time, many teams are handling large amounts of data from different departments.
Manual work makes these responsibilities harder.
Automation helps finance teams respond to modern business needs. It gives them better tools to handle growing workloads without depending only on more people and more spreadsheets.
1. Businesses Need Faster Financial Information
In the past, companies often waited until month-end or quarter-end to understand financial performance. Today, leaders want faster answers.
They want to know:
- How much money is coming in?
- How much money is going out?
- Which departments are over budget?
- Which customers have unpaid invoices?
- What is the current cash position?
- Are expenses increasing?
- Are there risks in the financial data?
Manual reporting can delay answers. Automation helps finance teams collect and process information faster, so management can make decisions based on current data rather than outdated reports.
2. Manual Data Entry Creates Errors
Accounting depends on accuracy. A small mistake in a number, date, invoice, tax amount, or account code can create problems later.
Manual data entry is one of the biggest sources of errors. When employees copy information from emails, PDFs, spreadsheets, receipts, and invoices, mistakes can happen easily.
Automation reduces the need to enter the same information again and again. It can also check data against rules and highlight unusual transactions.
3. Finance Teams Are Handling More Data
Modern companies generate large amounts of financial data. Sales systems, payroll systems, procurement platforms, banking portals, inventory tools, and customer management systems all create data.
When these systems are not connected, finance teams spend a lot of time collecting, cleaning, and combining information manually.
Automation helps connect systems and improve data flow. This allows finance professionals to spend more time analyzing information instead of preparing it.
4. Compliance Requirements Are Increasing
Businesses must follow tax rules, accounting standards, audit requirements, internal policies, and industry regulations. Finance teams need proper documentation and clear approval records.
Manual processes make it harder to prove who approved what, when a transaction happened, and whether policies were followed.
Automation creates digital records, approval trails, and system-based controls. This makes audits and compliance checks easier.
5. Companies Want Better Cost Control
Automation can help companies reduce unnecessary costs. When finance processes are slow and manual, companies may experience duplicate payments, missed discounts, late payment penalties, poor cash visibility, and inefficient reporting.
Automated systems help identify issues faster. They also help finance teams control spending and improve cash management.
How Automation Is Changing Daily Accounting Work
Automation is changing the daily routine of accounting teams. Many tasks that were once fully manual are now supported by software.
Accounts Payable
Accounts payable is the process of managing money that a company owes to suppliers. It includes receiving invoices, checking invoice details, matching invoices with purchase orders, getting approvals, and making payments.
In a manual system, accounts payable can be slow. Invoices may be lost in emails. Approvals may be delayed. Duplicate invoices may be paid by mistake. Payment deadlines may be missed.
Automation helps by:
- Capturing invoice data
- Matching invoices with purchase orders
- Routing invoices for approval
- Detecting duplicate invoices
- Tracking payment due dates
- Creating payment records
- Maintaining audit history
This makes supplier payments more accurate and efficient.
Accounts Receivable
Accounts receivable is the money a company expects to receive from customers. It includes creating invoices, sending payment reminders, recording payments, and managing overdue accounts.
Automation helps accounts receivable teams by:
- Creating invoices faster
- Sending automatic reminders
- Tracking unpaid invoices
- Matching payments to customer accounts
- Identifying late-paying customers
- Helping improve cash flow visibility
When accounts receivable is automated, companies can collect money faster and reduce manual follow-up work.
Bank Reconciliation
Bank reconciliation means comparing company accounting records with bank statements to make sure they match.
Manual reconciliation can take a long time because finance teams must check each transaction one by one.
Automation can match bank transactions with accounting entries and highlight differences for review. This saves time and helps identify errors faster.
Expense Management
Employees often submit expenses for travel, meals, transportation, software, or business supplies. In manual systems, employees submit receipts, managers approve them, and finance teams check the details.
Automation can simplify this process by allowing employees to upload receipts digitally, route expenses for approval, check policy rules, and update records automatically.
Payroll Support
Payroll must be accurate because employees depend on correct and timely payment. While payroll still requires careful review, automation can help with time records, deductions, benefits, tax calculations, and payroll reporting.
Automation reduces repetitive work and improves consistency in payroll-related finance tasks.
How Automation Is Changing Finance Teams
Accounting focuses on recording and processing financial information. Finance teams often focus more on planning, analysis, forecasting, budgeting, and business strategy. Automation is changing these areas too.
Financial Reporting
Financial reporting is one of the most important responsibilities of finance teams. Reports help leaders understand business performance.
Manual reporting often requires collecting data from different systems, copying it into spreadsheets, formatting reports, and checking formulas. This can take hours or days.
Automation allows reports to be generated faster. Dashboards and ERP systems can show real-time financial information, reducing the need for manual report preparation.
Budgeting and Forecasting
Budgeting is planning how money will be spent. Forecasting is estimating future financial performance based on current data and trends.
Automation helps finance teams prepare budgets and forecasts more efficiently. It can collect historical data, compare actual results with budgets, and highlight areas where spending is different from expectations.
With better tools, finance teams can create more accurate forecasts and update them more often.
Cash Flow Management
Cash flow is the movement of money in and out of a business. Even profitable companies can face problems if cash flow is poorly managed.
Automation helps finance teams monitor incoming payments, outgoing payments, due dates, and expected cash needs. This gives leaders better visibility into whether the company has enough cash to operate smoothly.
Financial Close
Financial close is the process of finalizing accounting records at the end of a month, quarter, or year. It includes reconciliations, adjustments, reviews, approvals, and reporting.
Manual financial close is often stressful because teams must complete many tasks in a short time.
Automation can help by:
- Tracking close tasks
- Assigning responsibilities
- Automating recurring journal entries
- Matching transactions
- Highlighting missing information
- Creating approval workflows
- Improving visibility into close progress
This helps companies close their books faster and with more confidence.
The Role of ERP Systems in Finance Automation
ERP stands for Enterprise Resource Planning. An ERP system connects different business functions such as finance, procurement, sales, inventory, HR, and operations.
For finance teams, ERP systems are very important because financial data comes from across the business. A sale affects revenue. A purchase affects expenses. Payroll affects costs. Inventory affects valuation. Customer payments affect cash flow.
When all these processes are connected, finance teams get more accurate and complete information.
SAP S/4HANA Finance is one example of a modern ERP finance solution. It helps organizations manage financial accounting, controlling, reporting, planning, compliance, and real-time insights in an integrated environment.
A key benefit of ERP systems is that finance is no longer separated from the rest of the company. Instead, finance teams can see how business activities affect financial results.
For learners who want to understand modern ERP-based finance processes, Toronto Innovation College offers SAP S/4HANA Finance Training designed to help learners understand financial processes, ERP workflows, reporting concepts, and enterprise finance operations.
The program focuses on practical SAP S/4HANA Finance concepts and business processes relevant to modern finance environments.
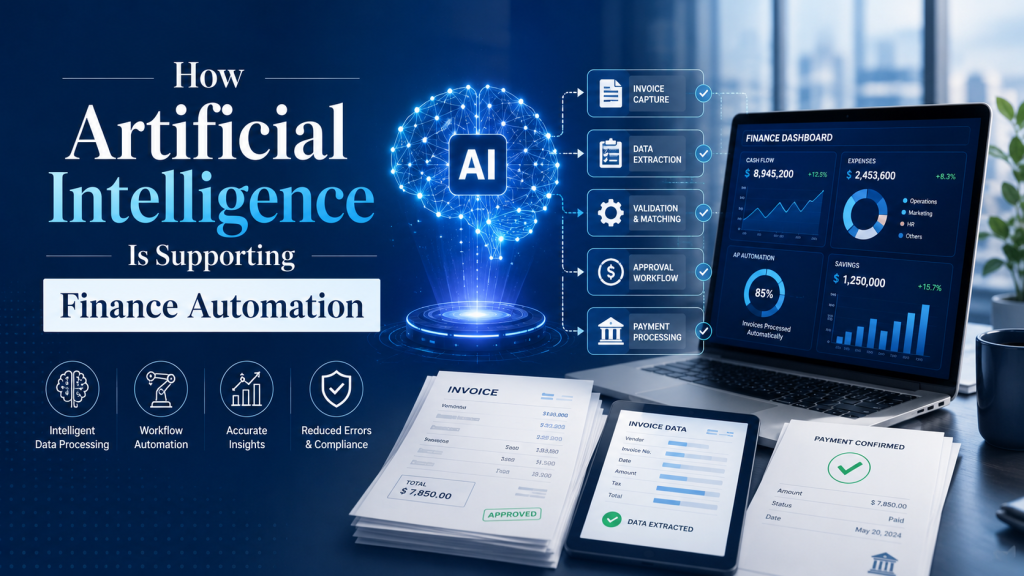
How Artificial Intelligence Is Supporting Finance Automation
Automation and artificial intelligence are connected, but they are not exactly the same.
Basic automation follows rules. For example, if an invoice is under a certain amount, send it to one manager for approval. If it is above a certain amount, send it to a senior manager.
Artificial intelligence can go further. AI can analyze patterns, detect unusual activity, predict outcomes, and help finance teams make better decisions.
AI can support finance teams by:
- Detecting possible fraud
- Identifying unusual transactions
- Predicting cash flow
- Supporting invoice processing
- Helping with financial forecasting
- Reading documents
- Summarizing financial information
- Supporting audit preparation
- Improving customer payment predictions
AI does not remove the need for finance professionals. In fact, human judgment becomes even more important. Finance professionals must understand whether AI suggestions make sense, whether data is reliable, and whether decisions are ethical and compliant.
Does Automation Replace Accounting Jobs?
This is one of the biggest questions students and professionals ask.
The simple answer is: automation changes accounting jobs, but it does not remove the need for accounting knowledge.
Repetitive tasks are becoming more automated. This includes data entry, invoice matching, basic reconciliations, report formatting, and routine calculations. But companies still need people who can understand financial information, review exceptions, explain results, manage compliance, and support decisions.
Automation may reduce some manual tasks, but it increases the importance of higher-value skills such as:
- Financial analysis
- Problem-solving
- Data interpretation
- Business communication
- ERP knowledge
- Process understanding
- Internal controls
- Risk awareness
- Tax and compliance knowledge
- Decision support
Finance professionals who only rely on manual processing may face challenges. But those who learn digital tools, ERP systems, and analytical thinking can become more valuable.
Skills Accounting and Finance Professionals Need in the Automation Era
As automation grows, the skill set for accounting and finance roles is changing.
1. Strong Accounting Basics
Technology is useful, but it cannot replace basic accounting knowledge. Professionals still need to understand debits, credits, journal entries, financial statements, tax concepts, payroll basics, accounts payable, accounts receivable, and reconciliations.
Without accounting fundamentals, it is difficult to know whether automated results are correct.
2. Excel and Spreadsheet Skills
Even with automation, Excel is still widely used in finance. Many teams use Excel for analysis, reporting, budgeting, and data review.
Finance professionals should know formulas, pivot tables, lookups, data cleaning, charts, and basic spreadsheet controls.
3. ERP System Knowledge
SAP S/4HANA Finance is one example of a modern ERP finance solution. It helps organizations manage financial accounting, controlling, reporting, planning, compliance, and real-time insights in an integrated environment.
A key benefit of ERP systems is that finance is no longer separated from the rest of the company. Instead, finance teams can see how business activities affect financial results.
For learners who want to understand modern ERP-based finance processes, Toronto Innovation College offers SAP S/4HANA Finance training designed to help learners understand financial processes, ERP workflows, reporting concepts, and enterprise finance operations.
The program focuses on practical SAP S/4HANA Finance concepts and business processes relevant to modern finance environments.
4. Data Analysis Skills
Finance teams are becoming more data-driven. Professionals need to understand how to read reports, compare trends, identify unusual numbers, and explain what the data means.
Data analysis helps finance teams move from record-keeping to business advising.
5. Process Understanding
Automation works best when people understand the full process. For example, invoice automation is easier to understand when you know how procurement, receiving, accounts payable, and payment approval connect.
Finance professionals should understand end-to-end processes, not just isolated tasks.
6. Communication Skills
Automation may create reports, but people still need to explain them. Finance professionals must communicate financial results to managers, business owners, and non-finance teams.
Clear communication is a major career advantage.
7. Critical Thinking
Automated systems can make mistakes if the data is wrong or the rules are not properly designed. Finance professionals must review results, question unusual numbers, and apply judgment.
Critical thinking is one of the most important human skills in automated finance.
Benefits of Automation for Businesses
Automation gives companies many benefits beyond saving time.
Improved Accuracy
Automation reduces manual data entry and helps prevent common mistakes. It also allows companies to build validation checks into processes.
Faster Decision-Making
When reports and dashboards are updated quickly, managers can make faster decisions.
Better Compliance
Automated workflows create approval records and audit trails. This helps companies prove that policies were followed.
Cost Savings
Automation can reduce time spent on repetitive tasks, duplicate payments, late fees, and inefficient reporting.
Better Employee Productivity
Finance teams can spend less time on routine work and more time on analysis, planning, and problem-solving.
Improved Cash Flow
Automation helps track payments, receivables, due dates, and expected cash needs.
Stronger Internal Controls
System-based approval rules and audit trails help reduce fraud risk and improve accountability.
Challenges of Finance Automation
Automation is powerful, but it is not perfect. Companies must manage it carefully.
Poor Data Quality
Automation depends on clean and accurate data. If supplier names, customer records, account codes, or invoice details are wrong, the system may create wrong results.
Overdependence on Technology
Teams should not blindly trust automated outputs. Human review is still necessary, especially for unusual transactions and important decisions.
Employee Training
Employees need training to use new systems properly. Without training, automation can create confusion instead of improvement.
System Integration
Finance systems often need to connect with payroll, procurement, sales, banking, inventory, and reporting tools. Integration can be complex.
Change Management
Some employees may resist automation because they are comfortable with manual processes. Companies need to communicate the benefits clearly and support staff during the transition.
Security and Privacy
Financial data is sensitive. Automation systems must be secure and properly controlled to protect business and customer information.
Real-Life Example: Manual Invoice Processing to Automated Invoice Processing
Imagine a company receives hundreds of supplier invoices every month.
In a manual process, the accounts payable team opens each invoice, enters details into a spreadsheet or accounting system, checks the purchase order, sends the invoice for approval, waits for the manager, updates payment status, and files the document.
This process can be slow and stressful.
In an automated process, invoices are uploaded or received electronically. The system reads the invoice details, checks them against purchase orders, sends approval requests, flags mismatches, updates records, and keeps a digital audit trail.
The finance team still reviews exceptions and approves important payments, but much of the repetitive work is reduced.
This allows the team to focus on problem-solving rather than data entry.
How Automation Improves Financial Reporting
Financial reporting becomes stronger when data is timely, accurate, and connected.
Manual reporting often has problems, such as:
- Outdated numbers
- Formula errors
- Missing data
- Version confusion
- Duplicate spreadsheets
- Slow report preparation
- Limited visibility
Automation improves reporting by connecting financial data directly from source systems. Reports can be refreshed more easily, dashboards can show current performance, and managers can track key financial indicators.
Good reporting helps companies understand revenue, expenses, profit margins, cash flow, department budgets, and business performance.
Why Automation Matters for Small and Medium-Sized Businesses
Automation is not only for large companies. Small and medium-sized businesses also benefit from finance automation.
Small businesses often have limited staff. One person may manage bookkeeping, invoices, payroll records, vendor payments, and reports. Manual work can quickly become overwhelming.
Automation helps smaller businesses:
- Stay organized
- Reduce errors
- Track cash flow
- Send invoices faster
- Manage expenses
- Prepare better records for tax time
- Improve financial visibility
- Save time on routine tasks
Even simple tools like cloud accounting software, digital receipt capture, automatic bank feeds, and invoice reminders can make a big difference.
Why Automation Matters for Canada’s Job Market
In Canada, many businesses use digital accounting tools, ERP systems, cloud software, and automated reporting platforms. Employers often look for candidates who understand both accounting basics and technology.
This is important for students, newcomers, and professionals who want to build accounting or finance careers. Traditional accounting knowledge is still important, but digital skills can improve job readiness.
Useful skills for Canada’s accounting and finance job market include:
- Bookkeeping knowledge
- Payroll basics
- Excel
- QuickBooks
- Sage
- SAP basics
- Financial reporting
- Data analysis
- ERP understanding
- Communication skills
- Compliance awareness
Automation is making finance roles more technical and analytical. People who are willing to learn modern tools can stand out.
Future of Accounting and Finance Teams
The future of accounting and finance will likely be more digital, connected, and analytical.
Finance teams will spend less time on repetitive processing and more time on:
- Explaining financial results
- Supporting business strategy
- Managing risk
- Forecasting future performance
- Improving processes
- Using data for decisions
- Monitoring compliance
- Working with AI tools
- Advising managers
The finance department of the future will not only record what happened. It will help predict what may happen next.
This shift makes finance professionals more important, not less important. But the skills required will continue to evolve.
Conclusion
Automation is changing accounting and finance teams by reducing manual work, improving accuracy, speeding up reporting, and helping companies make better decisions.
Tasks such as invoice processing, bank reconciliation, expense management, accounts receivable, financial reporting, budgeting, and closing are becoming more automated. This allows finance professionals to focus more on analysis, planning, compliance, communication, and strategic decision-making.
Automation does not remove the need for accounting and finance knowledge. Instead, it changes how that knowledge is used. Professionals who understand accounting basics, ERP systems, data analysis, and modern finance tools will be better prepared for the future.
For businesses, automation means faster processes, fewer errors, better control, stronger reporting, and improved financial visibility. For professionals, it means new opportunities to grow from manual processing roles into more analytical and technology-supported finance roles.
As finance continues to evolve, one thing is clear: accounting and finance teams are no longer just number-processing departments. They are becoming strategic partners in business growth.
To build practical knowledge of ERP-based finance workflows, explore the SAP S/4HANA Finance training program at Toronto Innovation College.
FAQs
1. What is automation in accounting and finance?
Automation in accounting and finance means using technology to complete repetitive financial tasks such as invoice processing, reconciliations, expense approvals, reporting, and payment tracking with less manual effort.
2. How is automation changing accounting jobs?
Automation is reducing repetitive tasks like data entry and manual matching. At the same time, it is increasing the need for skills in analysis, ERP systems, reporting, compliance, and business decision-making.
3. Will automation replace accountants?
Automation may replace some repetitive tasks, but businesses still need accountants and finance professionals to review results, apply judgment, manage compliance, explain reports, and support decisions.
4. What finance tasks can be automated?
Common tasks include accounts payable, accounts receivable, bank reconciliation, expense management, invoice matching, financial reporting, budgeting, forecasting, payroll data support, and financial close activities.
5. Why is SAP S/4HANA Finance important for modern finance teams?
SAP S/4HANA Finance helps connect financial data with business processes such as procurement, sales, inventory, and operations. Learning its practical concepts can help finance professionals better understand ERP workflows, reporting, financial control, and enterprise finance operations.
6. What skills are important for finance professionals in the automation era?
Important skills include accounting basics, Excel, ERP systems, SAP knowledge, data analysis, process understanding, communication, critical thinking, and compliance awareness.
7. Is automation useful for small businesses?
Yes. Small businesses can use automation for invoices, expense tracking, bank feeds, payroll records, payment reminders, and financial reporting.
8. How does automation improve financial reporting?
Automation improves reporting by reducing manual errors, connecting data sources, updating reports faster, and giving managers clearer financial visibility.
9. What is financial close automation?
Financial close automation helps manage month-end, quarter-end, or year-end closing tasks such as reconciliations, journal entries, reviews, approvals, and reporting.
10. How can finance professionals prepare for automation?
They can prepare by strengthening accounting knowledge, learning Excel, understanding ERP systems, improving data analysis skills, and staying updated with finance technology trends.